この商品を友人に教える:
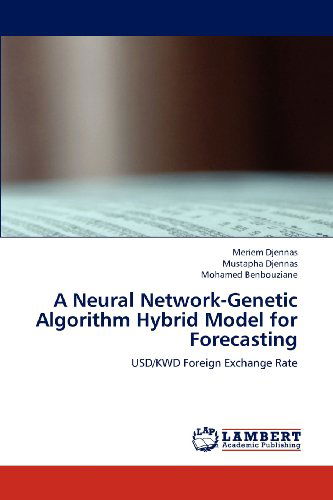
A Neural Network-genetic Algorithm Hybrid Model for Forecasting: Usd / Kwd Foreign Exchange Rate Mohamed Benbouziane
遠隔倉庫からの取り寄せ

A Neural Network-genetic Algorithm Hybrid Model for Forecasting: Usd / Kwd Foreign Exchange Rate
Mohamed Benbouziane
Prediction of exchange rate is one of the most leading financial problems because of its intrinsic difficulty and practical applications. In recent years, many nonlinear models have been proposed in the literature to modify the results of prediction in order to improve the forecasting performance of high frequency exchange rates. Neural networks and chaotic models are among models that have been exploited and have shown promising results. The main objective of our research is to conduct a comparative evaluation of nonlinear models on a series of data and variables and to verify the predictive power of neural models under the same experimental conditions. This study uses a criterion to evaluate the model performance: the root of the mean squared error. Our study will be applied on US-Dollar/Kuwaiti-Dinar exchange rate.
| メディア | 書籍 Paperback Book (ソフトカバーで背表紙を接着した本) |
| リリース済み | 2012年7月25日 |
| ISBN13 | 9783659196072 |
| 出版社 | LAP LAMBERT Academic Publishing |
| ページ数 | 56 |
| 寸法 | 150 × 3 × 226 mm · 102 g |
| 言語 | ドイツ語 |
